The key to retirement income? It’s not a number
Retirement planning is often framed as a math problem. But the most important factor isn’t your account balance or any other number—it’s what you plan to do with your money.
Retirement planning is often framed as a math problem. But the most important factor isn’t your account balance or any other number—it’s what you plan to do with your money.
A retirement plan isn’t a single goal—it’s a collection of them. Each reflects something different about the life you want to live. In our research paper Vanguard’s Principles for Retirement Income, we explain why the first step toward transforming your savings and investments into retirement income is determining your goals and understanding the challenges you could face in achieving them.
As you plan, keep in mind that goals often evolve over time. Reassess them periodically and update your plan as needed.
Retirement goals fall into three categories:
Needs are essential expenses such as housing, food, utilities, transportation, and health care. They are what you need to maintain your standard of living.
Wants are lifestyle expenses such as travel, dining, hobbies, and entertainment that increase your day-to-day enjoyment but can be trimmed if necessary.
Wishes are more aspirational goals such as supporting family or giving to charity. They should be considered after needs and wants.
For each of these categories, estimate how much you are likely to spend annually so that you can picture what your retirement expenses might look like. Be sure to include how much you’ll need as a contingency fund for unexpected expenses that can crop up such as medical costs, long-term care, or major home repairs.
Retirees’ spending can vary widely, shaped by location, health care needs, and lifestyle. In the first years of retirement, retirees spend about 80% of their pre-retirement income each year. For married couples, this translates to average spending of about $72,500.1 Averages provide a good starting point. But creating a stronger plan starts with capturing your actual expenses for housing, food, clothing, health care, taxes, and other essentials.
“Putting your purpose at the center of your plan helps you clarify your goals, account for key expenses, ensure your plan is sustainable, and prepare for the risks that could derail it,” said Boris Wong, a Vanguard investment strategist and lead author of the paper.
In practice, putting purpose first means deciding which expenses are essential and which are flexible. This is more than an organizational exercise. It helps you determine which expenses should be covered by guaranteed income and which can be adjusted depending on market, economic or other changes.
If there is one figure worth understanding deeply, it’s your portfolio withdrawal rate. That is the percentage of savings you withdraw from your portfolio each year to cover expenses beyond what reliable income sources will pay for. You can calculate it this way:
Calculate your initial portfolio withdrawal rate
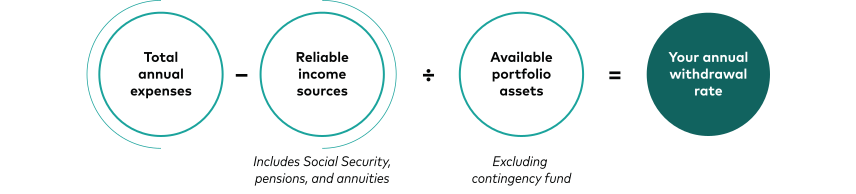
Vanguard’s retirement analysis shows that a withdrawal rate of roughly 3.5%–4% can support retirement for 30 years or more for many households. If your withdrawal rate is too high, it can significantly reduce how long your money will last. If it’s too low, you may miss out on enjoying your retirement as much as you could.
Life is unpredictable. You can never be sure whether inflation will rise or fall, or if a visit to the emergency room will leave you with a big medical bill. But you can lessen the chance that events like these will throw your retirement off course. Incorporating an inflation estimate into your spending projections and holding a diversified portfolio of stocks, bonds, and cash can help you cope with inflation, for example. Your contingency fund can cover unexpected expenses.
One surprisingly big risk is the number of years you will spend in retirement. People are living longer, healthier lives. That’s a positive change, but it means that your retirement income likely will need to last for many years. Our calculations show that outliving your savings can pose a bigger risk than weak investment returns.
Under both typical and poor market conditions, a diversified portfolio of $1 million with 2% annual inflation adjustments and a 6% withdrawal rate starting at age 66 can last approximately 20 years. If retirement extends to 30 years, however, savings could run out—under either market scenario.
Longevity can pose a bigger risk than poor market returns
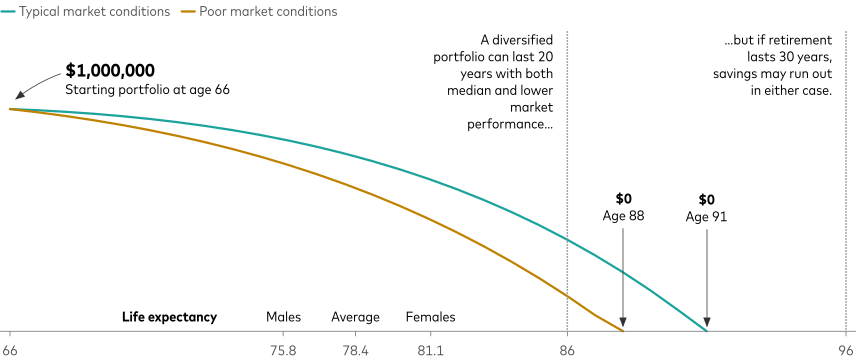
Notes: The figure assumes a 66-year-old retiree with a starting portfolio of $1,000,000. The withdrawal amount is initially 6% of the portfolio and increases by 2% annually to account for inflation. The average 30-year geometric return is calculated for a static portfolio composed of 50% equities (60% U.S. and 40% international) and 50% bonds (70% U.S. and 30% international), with median performance at the 50th percentile (5.80% annualized) and poor performance at the 25th percentile (4.81% annualized). The projections shown are based on Vanguard Capital Markets Model® (VCMM) simulations run on February 28, 2026. These results are hypothetical, do not reflect actual investment performance, and are not guarantees of future outcomes.
Sources: Vanguard, using data from the Society of Actuaries.
IMPORTANT: The projections and other information generated by the VCMM regarding the likelihood of various investment outcomes are hypothetical in nature, do not reflect actual investment results, and are not guarantees of future results. Distribution of return outcomes from VCMM are derived from 10,000 simulations for each modeled asset class. Simulations as of February 28, 2026. Results from the model may vary with each use and over time. For more information on the VCMM, please see the Notes section at the end of this article.
You can temper both longevity and market risk by covering essential expenses with guaranteed income sources—such as Social Security, pensions, and annuities.
Numbers like your portfolio withdrawal rate and annual expenses are important, but before you start filling spreadsheets with data, decide what you want out of retirement, for both you and your loved ones. Remember to reevaluate your goals periodically and readjust if necessary. Once you have established your priorities—essential expenses secured, lifestyle spending planned, legacy wishes considered—you can more easily navigate the path to a sustainable income plan.
Notes:
1Data based on the RAND Health and Retirement Survey (HRS), a nationally representative longitudinal study that collects financial, spending, health, and socioeconomic data from U.S. adults age 50 and older every two years.
All investing is subject to risk, including possible loss of principal. Be aware that fluctuations in the financial markets and other factors may cause declines in the value of your account. There is no guarantee that any particular asset allocation or mix of funds will meet your investment objectives or provide you with a given level of income.
Diversification does not ensure a profit or protect against loss.
IMPORTANT: The projections and other information generated by the Vanguard Capital Markets Model (VCMM) regarding the likelihood of various investment outcomes are hypothetical in nature, do not reflect actual investment results, and are not guarantees of future results. VCMM results will vary with each use and over time.
The VCMM projections are based on a statistical analysis of historical data. Future returns may behave differently from the historical patterns captured in the VCMM. More importantly, the VCMM may be underestimating extreme negative scenarios unobserved in the historical period on which the model estimation is based.
The VCMM is a proprietary financial simulation tool developed and maintained by Vanguard's primary investment research and advice teams. The model forecasts distributions of future returns for a wide array of broad asset classes. Those asset classes include U.S. and international equity markets, several maturities of the U.S. Treasury and corporate fixed income markets, international fixed income markets, U.S. money markets, U.S. municipal bonds, commodities, and certain alternative investment strategies. The theoretical and empirical foundation for the Vanguard Capital Markets Model is that the returns of various asset classes reflect the compensation investors require for bearing different types of systematic risk (beta). At the core of the model are estimates of the dynamic statistical relationship between risk factors and asset returns, obtained from statistical analysis based on available monthly financial and economic data from as early as 1960. Using a system of estimated equations, the model then applies a Monte Carlo simulation method to project the estimated interrelationships among risk factors and asset classes as well as uncertainty and randomness over time. The model generates a large set of simulated outcomes for each asset class over time. Forecasts represent the distribution of geometric returns over different time horizons. Results produced by the tool will vary with each use and over time.
Publication date: September 2026
The information contained in this material may be subject to change without notice and may not represent the views and/or opinions of Vanguard Investments Canada Inc.
Certain statements contained in this material may be considered "forward-looking information" which may be material, involve risks, uncertainties or other assumptions and there is no guarantee that actual results will not differ significantly from those expressed in or implied by these statements. Factors include, but are not limited to, general global financial market conditions, interest and foreign exchange rates, economic and political factors, competition, legal or regulatory changes and catastrophic events. Any predictions, projections, estimates or forecasts should be construed as general investment or market information and no representation is being made that any investor will, or is likely to, achieve returns similar to those mentioned herein.
While the information contained in this material has been compiled from proprietary and non-proprietary sources believed to be reliable, no representation or warranty, express or implied, is made by The Vanguard Group, Inc., its subsidiaries or affiliates, or any other person (collectively, "The Vanguard Group") as to its accuracy, completeness, timeliness or reliability. The Vanguard Group takes no responsibility for any errors and omissions contained herein and accepts no liability whatsoever for any loss arising from any use of, or reliance on, this material.
This material is not a recommendation, offer or solicitation to buy or sell any security, including any security of any investment fund or any other financial instrument. The information contained in this material is not investment advice and is not tailored to the needs or circumstances of any investor, nor does the information constitute business, financial, tax, legal, regulatory, accounting or any other advice.
The information contained in this material may not be specific to the context of the Canadian capital markets and may contain data and analysis specific to non-Canadian markets and products.
The information contained in this material is for informational purposes only and should not be used as the basis of any investment recommendation. Investors should consult a financial, tax and/or other professional advisor for information applicable to their specific situation.
In this material, references to "Vanguard" are provided for convenience only and may refer to, where applicable, only The Vanguard Group, Inc., and/or may include its subsidiaries or affiliates, including Vanguard Investments Canada Inc.